Medically reviewed by Barbra Scheirer,
Psychiatric Mental Health Nurse Practitioner at Mighty Mental Health
Last medically reviewed: September 15, 2026
Most health insurance plans, including employer plans, ACA marketplace plans, Medicare, and Medicaid, cover psychiatric care such as evaluations, medication management, and follow-up visits.
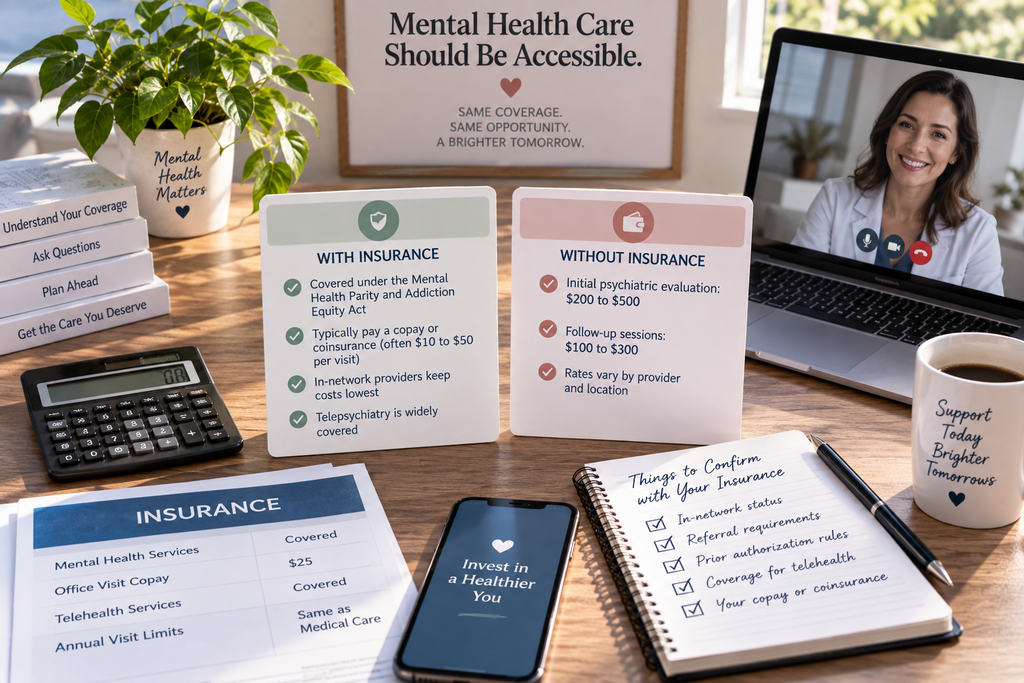
The Mental Health Parity and Addiction Equity Act requires insurers to cover mental health services at the same level as other medical care, so copays and visit limits should be comparable. With insurance, patients typically pay only a copay or coinsurance, often $10 to $50 per visit, while an in-network provider keeps costs lowest.
Without insurance, psychiatric evaluations generally run $200 to $500, with follow-up sessions between $100 and $300, though rates vary by provider and location. Coverage details still depend on the specific plan, so confirming network status, referral requirements, and prior authorization rules ahead of time helps avoid surprise costs. Telepsychiatry is now widely covered as well.
Why Understanding Psychiatry Coverage Matters
Mental health is just as important as physical health, yet cost concerns keep many people from booking that first appointment. Two questions come up again and again: is a psychiatrist covered by insurance, and how much will a visit actually cost? The answers depend on the type of plan, whether the provider is in-network, and what kind of care is being provided. This guide combines both into one reference so you can understand coverage rules and pricing before you schedule a visit.
Is Psychiatry Usually Covered by Insurance?
In most cases, yes. Mental health coverage in the United States has expanded significantly over the past decade. The Mental Health Parity and Addiction Equity Act (MHPAEA) requires most insurance plans to cover psychiatric services at the same level as other medical care, meaning copays, deductibles, and visit limits should be comparable to a standard doctor visit.
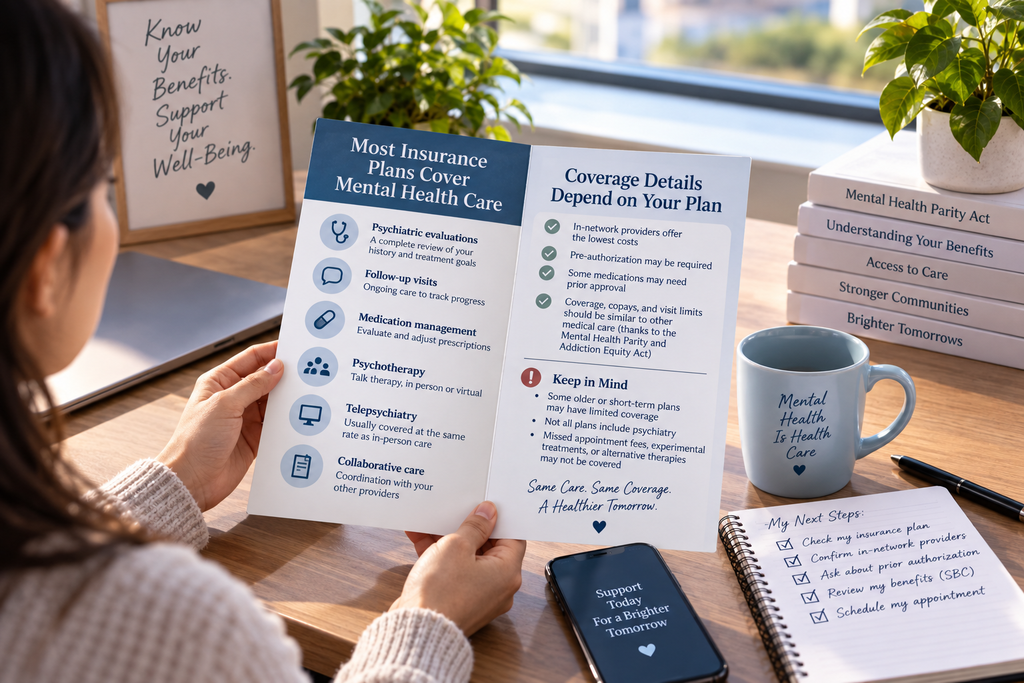
That said, not every plan is equal. Some older employer plans, short-term policies, or low-cost catastrophic plans may limit mental health coverage or exclude psychiatry altogether. Even when psychiatry is covered, plans commonly require:
- Seeing an in-network psychiatrist for full benefits
- Pre-authorization before the first visit
- Prior approval for certain medications
Parity law requires equal coverage, but it does not require insurers to maintain large provider networks, so availability can still be limited depending on your plan.
What Insurance Typically Covers
When psychiatric visits are covered, plans generally include:
- Initial psychiatric evaluation – a full review of medical and mental health history, current symptoms, and treatment goals
- Follow-up visits – ongoing sessions to track progress and adjust care
- Medication management – evaluating and adjusting prescriptions as needed
- Psychotherapy – talk therapy, either provided directly or through a referral
- Telepsychiatry – virtual visits, usually covered at the same rate as in-person care
- Collaborative care – coordination between your psychiatrist and other providers
Coverage typically excludes missed appointment fees, experimental or non-FDA-approved treatments, and alternative therapies not considered standard psychiatric care. Your plan’s Summary of Benefits and Coverage (SBC) is the most reliable place to confirm specifics.
How Coverage Varies by Insurance Type
- Employer-sponsored insurance usually includes mental health coverage with a network of approved psychiatrists. Staying in-network keeps copays and deductibles lower.
- ACA marketplace plans are required to include mental health care as an essential health benefit, covering both in-person and telehealth psychiatric visits.
- Medicare Part B covers outpatient psychiatric services, including evaluations, medication management, and psychotherapy, though a copay or coinsurance applies after the deductible.
- Medicaid coverage varies by state but generally includes psychiatric care, particularly for serious mental health needs. Some states cap the number of covered visits per year.
- Private individual plans purchased outside an employer or the ACA marketplace vary widely in generosity, so it is worth reviewing the plan documents closely.
How Much Does a Psychiatrist Cost With Insurance?
With insurance, most patients are responsible only for a copay or coinsurance. Copays commonly range from $10 to $50 per session. Coinsurance instead requires paying a percentage of the visit cost, for example 20 percent of a $200 session, or $40 out of pocket. Actual costs depend on your deductible status and whether the provider is in-network, since out-of-network care is typically far more expensive.
Special testing, such as advanced diagnostic or neuropsychological assessments, often falls outside routine coverage and may require separate billing or prior authorization.
How Much Does a Psychiatrist Cost Without Insurance?
Without insurance, patients pay the full provider rate, which varies by location and practice. Nationally, an initial evaluation typically runs $200 to $500, while follow-up visits range from $100 to $300.
At Mighty Mental Health, self-pay rates are:
- $250 for the initial psychiatric evaluation
- $125 per follow-up session
These rates are set with transparency in mind, with no hidden fees. Special assessments or testing are billed separately, with quotes available on request.
Some patients choose to self-pay even when they have insurance, since it removes network restrictions, session caps, and pre-authorization delays, offering more flexibility over the treatment experience.
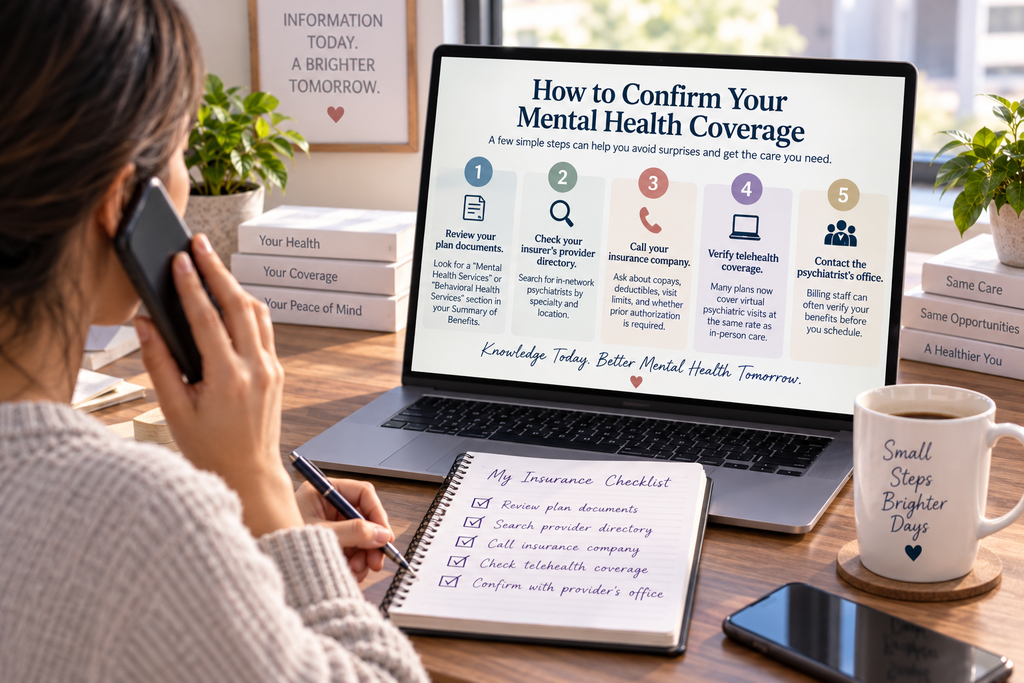
How to Confirm Your Coverage
- Review your plan documents. Look for a “Mental Health Services” or “Behavioral Health Services” section in your Summary of Benefits.
- Check your insurer’s provider directory. Search for in-network psychiatrists by specialty and location.
- Call your insurance company. Ask directly about copays, deductibles, visit limits, and whether prior authorization is required.
- Verify telehealth coverage. Many plans now cover virtual psychiatric visits at the same rate as in-person care.
- Contact the psychiatrist’s office. Billing staff can often verify your benefits before you schedule.
Finding Affordable Psychiatric Care Without Insurance
- Look for transparent self-pay pricing so you can budget with confidence before booking.
- Consider community mental health clinics, which often offer sliding-scale fees based on income, though wait times may be longer.
- Explore telepsychiatry, which frequently costs less than in-person care, sometimes starting around $99 per session.
- Ask about payment plans if cost is still a barrier; many practices offer installment options.
Psychiatric Care at Mighty Mental Health
Mighty Mental Health provides psychiatric care through providers who accept Nevada Medicaid, CareSource, Silver Summit, Health Plan of Nevada, Molina, and Anthem, along with transparent self-pay options for patients without coverage. Our Psychiatric Nurse Practitioner, Barbra Scheirer, works with each patient to build a treatment plan that may include medication management, therapy referrals, or both.
We serve patients across Las Vegas and Summerlin, NV, with both in-office consultations and Telehealth visits. To confirm your benefits or schedule an appointment, call 702-479-1600 or reach out through our contact form. Contact us now!
Frequently Asked Questions
Does insurance cover therapy in addition to psychiatric visits?
Many plans cover psychotherapy alongside psychiatric care, either provided directly by the psychiatrist or through a referral to a licensed therapist. Coverage details depend on your specific plan.
Do I need a referral to see a psychiatrist?
It depends on your plan. Some insurance plans, particularly HMOs, require a referral from a primary care provider, while PPO plans often allow direct scheduling with a psychiatrist.
Is telepsychiatry covered the same as in-person visits?
In most cases, yes. Many insurers now reimburse virtual psychiatric visits at the same rate as in-office appointments, though it is worth confirming with your specific plan.
What should I do if my insurance denies coverage for a psychiatric visit?
You can request a written explanation from your insurer, ask your provider’s billing office for help appealing the decision, and, if needed, file a formal appeal with supporting documentation from your psychiatrist.
References
- U.S. Department of Labor, Mental Health Parity and Addiction Equity Act (MHPAEA)
- Centers for Medicare & Medicaid Services (CMS), Medicare Part B Mental Health Coverage
- HealthCare.gov, Mental Health & Substance Abuse Coverage
- Medicaid.gov, Behavioral Health Services